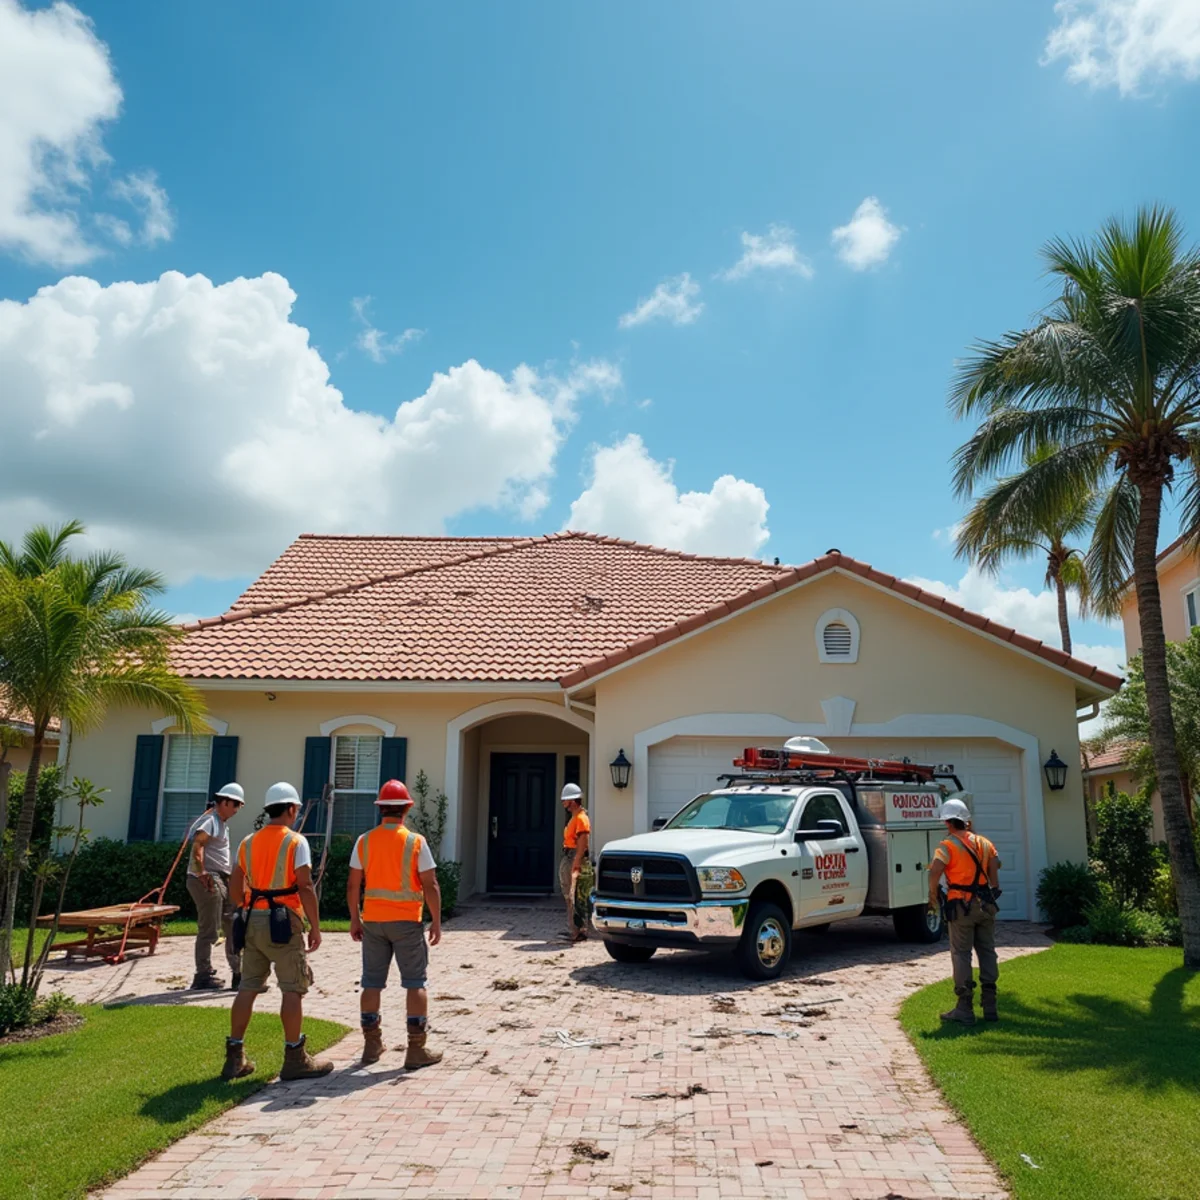
When a hurricane or a strong tropical storm rolls over Palm Beach County, roofs take the first hit. Boca Raton sits in a roughly 170 mph ultimate design-wind zone, and even a glancing storm can lift tile, peel a flat membrane, drive water under the covering, and leave decking exposed. The moment it is safe to be outside, call (831) 666-1600. We prioritize securing your roof, then document the damage properly so your insurance claim starts on solid ground.
Speed and documentation both matter after a storm. Getting a tarp or dry-in on quickly protects the inside of your home and meets your policy's duty to prevent further damage. But rushing to strip and rebuild before anything is photographed can cost you on the claim. We balance the two: stabilize first, document thoroughly, then repair or replace to current code once the scope and coverage are clear.
Signs you need hurricane damage in Boca Raton
Missing and cracked tile
Uplift and flying debris crack and dislodge tile in sections. Because many older Boca profiles are discontinued, widespread tile loss often points toward replacing a slope rather than patching it.
Lifted or peeled membrane and shingles
Wind catches the edge of a flat membrane or a shingle field and rolls it back, exposing the underlayment and deck to the rain bands that follow the eye.
Exposed and damaged decking
When the covering goes, the sheathing underneath can be soaked, split by debris, or found to be under-nailed. It has to be dried, inspected, and re-secured to code.
Hidden water intrusion
The worst storm damage is often invisible from the street: water that traveled into the attic, insulation, and wall cavities and will grow mold if it is not found and dried within a day or two.
Our process
- 1
Emergency stabilization
First we make the roof safe and watertight with a properly fastened tarp or dry-in. Our <a href="/roof-tarping/">roof tarping service</a> covers how we secure large storm openings so they hold through the follow-on rain.
- 2
Full damage documentation
We fly a drone and photograph every damaged area, dated and detailed, before removing anything. This record is what supports a fair insurance claim later.
- 3
Code and 25% rule assessment
We assess whether a repair is code-compliant or whether Florida's 25% rule requires bringing the whole roof section up to the current code, and we explain which applies to your roof.
- 4
Insurance coordination
We provide the photo report and a written scope, and we can meet your adjuster on the roof. Our <a href="/roof-insurance-claims/">insurance claim support</a> walks through that process honestly.
- 5
Code-compliant repair or replacement
We rebuild to the 2023 Florida Building Code with product-approved materials, re-nailed decking, and wind-rated fastening, then hand off permits and warranty documents.
Do not sign anything before the roof is documented
After a major storm, out-of-town crews and storm chasers flood South Florida and pressure homeowners to sign contracts or assignment-of-benefits forms on the spot. Slow down. Confirm you are dealing with a Florida state-certified, insured contractor by checking the license at myfloridalicense.com, where legitimate certified roofing licenses begin with the letters CCC. A local company that will still be here for the warranty is worth more than a fast-talking door knocker.
The first practical step is documentation. We photograph the full extent of the damage before touching the roof, because once a slope is stripped for repair, the evidence of what the storm did is gone. Our guide on the first 24 hours after hurricane roof damage lays out exactly what to do and in what order.
The 25% rule and rebuilding to current code
Florida's 25% rule, which comes from the building code and was tightened by SB 4-D in 2022, says that if more than a quarter of a roof section is repaired or replaced within 12 months, the whole section generally has to be brought up to the current code. After a hurricane, that threshold is easy to cross, so a repair you assume is small can trigger a full-section upgrade. Roofs already built or reroofed to the 2007 code or later may be exempt from full replacement.
We assess which side of that line your roof falls on before you commit, and we explain it in plain English. If replacement is required or simply the better value, we handle it as a full roof replacement with the wind-mitigation features that can also lower your premium. Our guide to the 25% roof rule covers the exemptions in more detail.
Hurricane Damage across Palm Beach & Broward County
After a named storm we mobilize across both counties, prioritizing the hardest-hit roofs. We handle post-hurricane damage in Delray Beach and Boynton Beach in Palm Beach County, and in Deerfield Beach, Pompano Beach, and Coral Springs across the Broward line. Response times stretch when a storm hits the whole region at once, and we are straight with you about the window when you call.
Hurricane rebuilds are where the HVHZ line really matters. A re-roof in Deerfield Beach or anywhere in Broward must use HVHZ-approved products with a Miami-Dade NOA and the stricter fastening the zone demands. Boca Raton and the rest of Palm Beach County build to the roughly 170 mph design wind speed under Florida Product Approval, outside the HVHZ. Either way, Florida's 25% rule can turn a large repair into a full-section replacement, and we tell you which code path your roof falls under before work starts.
What affects your price
Post-storm work spans a quick emergency tarp to a full re-roof, so cost varies widely. Emergency mitigation is often reimbursable on a covered claim. Every scope is priced in writing after we document the damage.
- Extent of damage
- A dozen cracked tiles is a repair; a stripped slope with soaked decking is a partial or full replacement.
- The 25% rule
- If storm repairs touch more than a quarter of a roof section in 12 months, that section generally must be brought to current code, which changes the scope.
- Decking condition
- Wet, split, or under-nailed sheathing found during tear-off is replaced at a per-sheet rate you approve in advance.
- Material and product approval
- Matching tile, and the code-required underlayment and fastening upgrades, factor into both cost and lead time.
- Insurance coverage
- What your policy covers, your deductible, and any depreciation held back all shape your out-of-pocket cost, which we help you understand.
These are honest planning ranges, not a quote. Your written scope confirms the real price after a free inspection. Call (831) 666-1600.
Why choose Mighty Dog Roofing for hurricane damage
- Fast post-storm stabilization to stop further interior damage
- Thorough dated photo documentation before anything is removed
- Straight answers on repair versus replacement and the 25% rule
- Rebuilt to the 2023 Florida Building Code with wind-rated fastening
- We coordinate with your adjuster and provide the paperwork your carrier needs
- Florida state-certified, insured contractor who pulls the permits and schedules inspections